UK’s 2027 crypto rules let firms remove trust protection from Bitcoin lent for yield
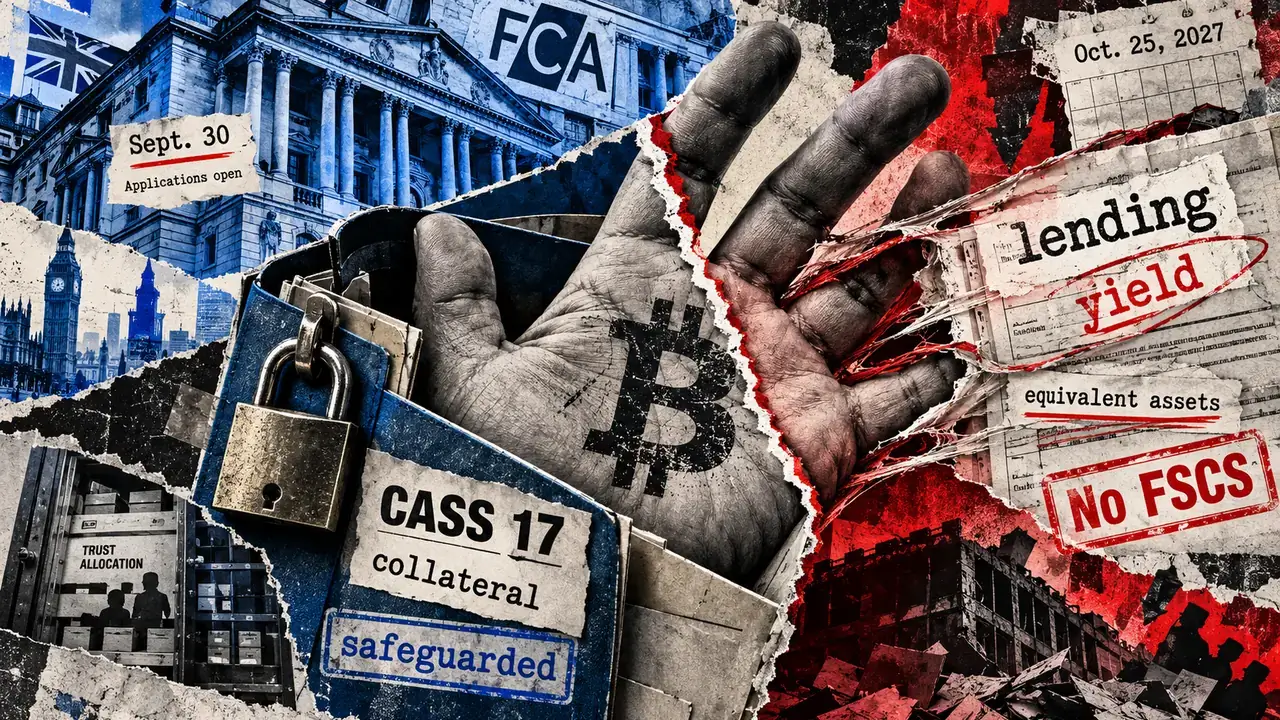
UK crypto firms can now apply for authorization as of Sept. 30, bringing Bitcoin holders closer to a rulebook that will treat coins pledged as qualifying borrowing collateral differently from coins transferred into lending for yield. The distinction could matter when a platform fails: safeguarded assets and a contractual promise to return equivalent coins give customers different starting points for seeking recovery.
The Financial Conduct Authority now allows firms to apply for authorization or vary their permissions through its Connect system. But the safeguards in the rules it finalized June 30 are forthcoming, with the new regime expected to begin Oct. 25, 2027. An application today does not establish authorization or bring those protections into effect.
The central distinction concerns what a platform is allowed to do with customer assets. Under the future rules, covered custody generally requires a safeguarding trust under CASS 17, the crypto custody chapter of the FCA's Client Assets Sourcebook. Retail collateral supporting an in-scope crypto borrowing service must remain safeguarded, with a narrow debt-discharge exception. A qualifying lending service can instead use an exemption from the trust requirement while the lending continues. The collateral protection concerns qualifying cryptoasset borrowing, a defined service; it cannot automatically be extended to every cash loan marketed as Bitcoin-backed.
The different legal basis for asking for coins back matters when assets are missing. Recovery still depends on whether the failed firm has enough assets to return, and the newly regulated crypto activities will remain outside Financial Services Compensation Scheme coverage.
Pledged coins must remain safeguarded
Under the forthcoming framework, the FCA's retail collateral rule requires a firm providing qualifying cryptoasset borrowing to arrange safeguarding for relevant crypto collateral. It can safeguard the assets itself if it has the necessary permission, or arrange for an appropriately authorized custodian to do so if it has permission to arrange safeguarding.
For Bitcoin used as collateral in such an arrangement, the firm cannot simply obtain full ownership so it can deploy the coins elsewhere. The rule prevents either the firm or another person taking full ownership unless the retail client has given express prior consent to an ownership transfer to discharge debt arising from that borrowing service.
The associated debt-discharge provision adds another condition. A written, binding agreement must give the firm the right to take ownership to discharge an obligation, and the firm must actually exercise that right according to the agreement. Until the firm exercises that agreed right, merely signing the agreement leaves the coins subject to the safeguarding requirement.
The practical consequence is that pledging coins does not automatically turn them into the platform's freely usable inventory. The safeguarding obligation continues unless a permitted change in their treatment occurs. Borrowing against coins therefore needs to be distinguished from handing them over for a yield-generating lending service.
For a borrower comparing products, the legal classification therefore matters. These provisions concern qualifying cryptoasset borrowing, a defined service whose treatment depends on the substance of the arrangement. The FCA's perimeter guidance says the legal substance of an arrangement and the roles of its participants determine its characterization. The retail collateral rule cannot automatically be read across to every cash loan secured by Bitcoin.
The retail and wholesale boundaries also differ. The core lending and borrowing chapter generally applies to retail clients who are not overseas retail clients, while certain records and transfer requirements have broader application to clients who are not overseas clients.
Lending can change the customer's claim
Qualifying cryptoasset lending moves assets in the other direction. In the FCA's description, a person disposes of cryptoassets to or through another person, with an obligation or right to reacquire the same or equivalent assets, typically earning yield.
That return right is different from an instruction to keep coins in custody. Under CASS 17.3.4, a firm providing a qualifying lending service can be exempt from acting as trustee for those assets during the service. If it already holds them in a safeguarding trust, the rule allows it to stop treating them as client cryptoassets while the exemption applies.
The exemption ends when the lending service ends, including where the client exercises a right to terminate it. Actual return still depends on the availability of coins, the agreed return timing and access restrictions. Ending the service therefore leaves practical questions about when the customer can receive the assets owed.
Crucially, the lending exemption cannot be used for qualifying borrowing collateral. A separate exemption for other services requiring an ownership transfer is also unavailable for that collateral. The rulebook therefore prevents those routes from undermining the collateral safeguard.
For a customer whose coins have been transferred into lending outside the required trust, a CASS 17 trust claim cannot be assumed. Recovery may instead depend on the contractual return right and the applicable insolvency treatment. The contract and service structure determine the particular claim; the exemption does not assign every lending customer the same creditor ranking.
The FCA's forthcoming information requirements make this distinction part of the customer explanation. Firms must provide information about transfer and return, access, yield and risks. Its guidance also calls for explaining the implications of ownership transfers, including what happens if the firm or another relevant party becomes insolvent.
For a customer earning yield, the agreement is central to understanding the claim behind the balance shown on an app. It needs to establish whether the coins remain safeguarded, whether ownership changes and what must be returned when the service ends.
Custody recovery still depends on assets and costs
For covered custody, CASS 17 generally requires the firm to safeguard cryptoassets as trustee under documented arrangements. The FCA explains that trusts are intended to protect clients' rights against competing claims, including when the custodian becomes insolvent.
The rules require firms to establish private trusts through the relevant legal arrangements. The safeguarding obligation depends on those arrangements being put in place, rather than on a statutory trust arising automatically from the rules. Those arrangements and their operation still have to satisfy the specified legal and safeguarding requirements.
The asset boundary is also important. CASS 17's application rules concern regulated activities carried on from a UK establishment, subject to exceptions. The FCA's final-policy overview says custody of relevant specified investment cryptoassets will initially follow the separate CASS 6 requirements. Different assets and service structures can therefore fall under different custody provisions.
Records help establish what belongs in the trust. The forthcoming reconciliation requirements include calculating what a firm must hold for each client, trust and asset class at least once each business day. That supports identifying entitlements, but identifying an entitlement is different from having all the assets needed to satisfy it.
Trust terms must specify how shortfalls are allocated where several clients share a trust. They must also state whether client assets can pay distribution costs following trustee failure and, if so, how those deductions work. The FCA generally expects a shortfall within an asset class in a trust to be shared proportionally among the affected clients.
Those provisions make the recovery limit concrete. A trust can strengthen the basis for an asset claim without ensuring full repayment after losses or costs.
Staking should also be distinguished from lending. The FCA's collateral guidance says staking eligible collateral should remain possible only with compliance with the staking rules, no transfer of full ownership and continued trust safeguarding. That conditional treatment does not create a lending exemption for borrowing collateral.
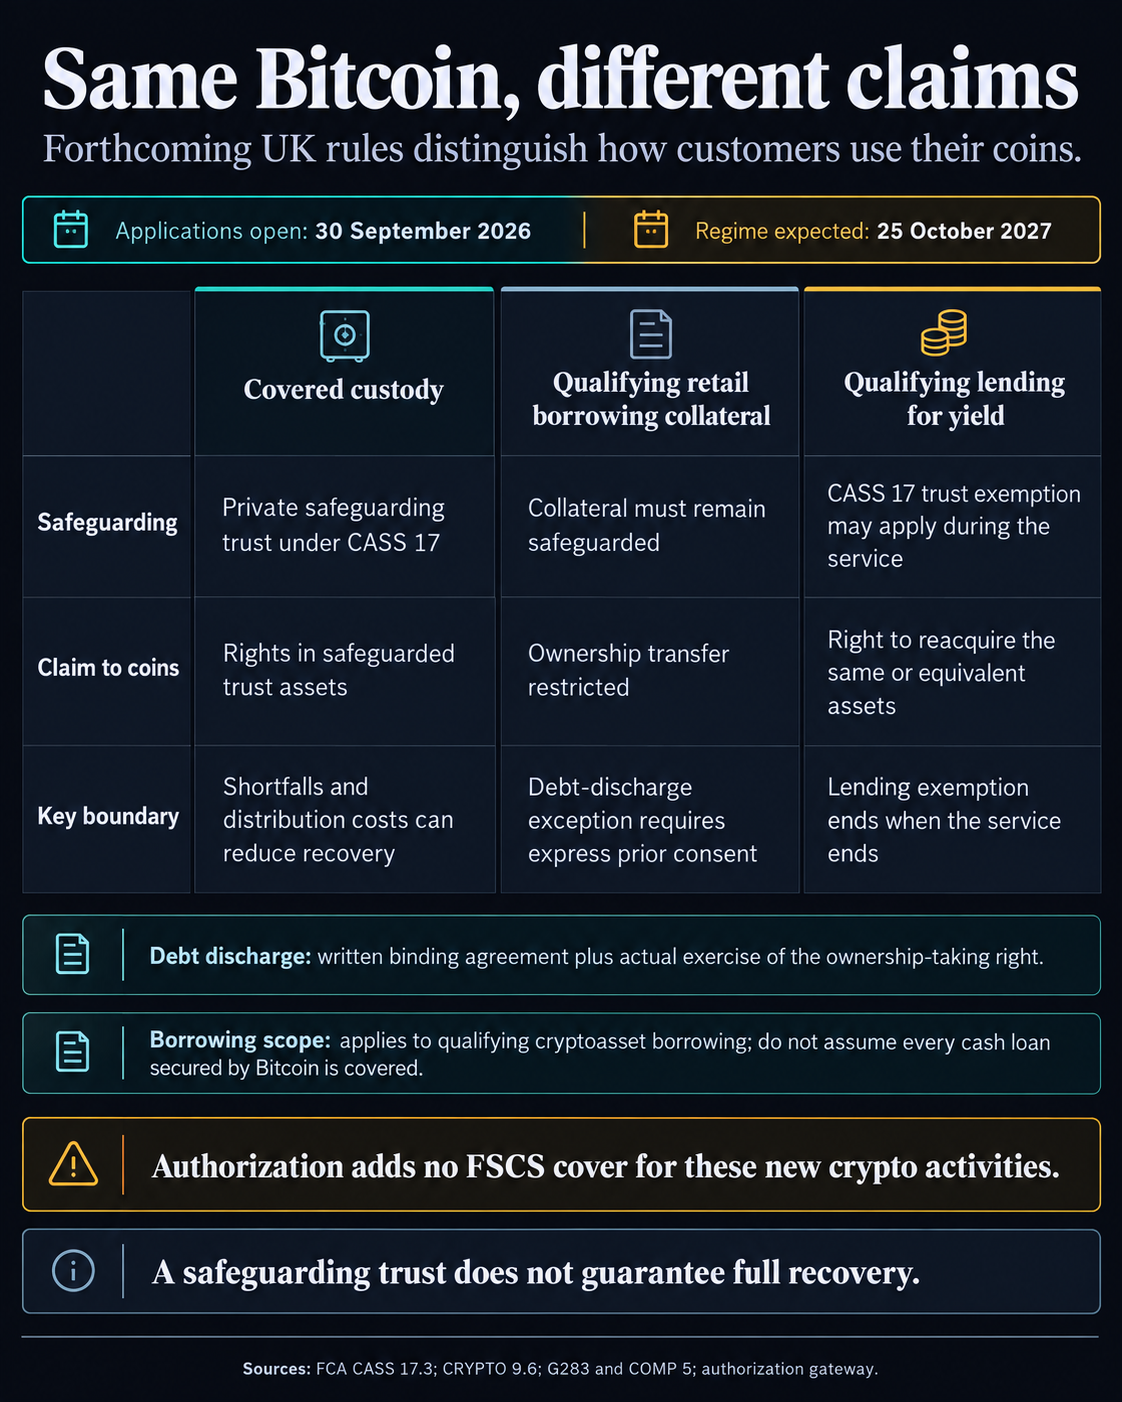
Authorization will not add FSCS insurance
The compensation boundary survives the move to authorization. In the future Handbook glossary, the FCA brings the new crypto activities into the definition of designated investment business for general Handbook purposes, then expressly excludes them when that definition is used in the compensation rules.
The exclusions include crypto safeguarding, arranging safeguarding, operating trading platforms, dealing and arranging deals in qualifying cryptoassets, stablecoin issuance and arranging staking. Together with the protected-claim rules, that means authorization for these new activities does not add FSCS investment compensation protection.
A firm could conduct other business with different compensation eligibility. Its authorization for an uncovered crypto service, however, cannot turn that service into a covered investment claim.
The Financial Ombudsman Service is a separate route. DISP's jurisdiction rules can permit eligible complaints about regulated activities, subject to the applicable conditions. An eligible complaint addresses the firm's conduct. Payment of any award still depends on the circumstances, while FSCS eligibility remains a separate question.
Earlier coverage examined the authorization timetable and the stablecoin and lending perimeter.
Overseas platform access is another part of the regulatory picture. For customers, the next question is how the particular service treats their assets after a firm gains the permissions it needs.
The FCA also said in its June policy overview that it would consult later in 2026 on managing cryptoasset firm failures, including distribution rules for failed custodians and stablecoin issuers. The shape of the failure and distribution framework will also matter to the practical outcome for customers.
As applications open, the distinction for Bitcoin holders is between access to a regulated service and the rights attached to their coins within it. Custody, qualifying borrowing collateral and lending for yield can lead to different asset claims. The October 2027 framework will make that distinction more explicit, while leaving recovery dependent on the arrangement, the assets available and the applicable failure process.
The post UK’s 2027 crypto rules let firms remove trust protection from Bitcoin lent for yield appeared first on CryptoSlate.