Solana flips Ethereum in fees, while ETH holds the burn lead
Solana generated more user fees than Ethereum in data provider DefiLlama's Sept. 22 dashboard snapshot, while Ethereum burned more fees. The split shows that users' spending can reach validators and applications without producing an equivalent benefit for someone simply holding the network's coin.
The data provider's Solana overview showed about $1.1 million in chain fees over 24 hours and $117,138 in reported chain revenue. Ethereum's overview showed $649,423 in fees and $226,298 in revenue.
For these two networks, the revenue measure tracks fees reported as burned, removing tokens from supply without paying holders cash.
Solana also led on displayed seven-day and 30-day fees, while Ethereum retained a smaller lead in reported burns. Yet the dollar ranking does not settle which token offers better economics: new issuance, network value, and the share of validator income reaching stakers all change the comparison.
DefiLlama's chain fee table put Solana at $23.6 million over 30 days, compared with Ethereum's $12 million. Its chain revenue table showed a burn comparison of $2.66 million for Solana and $2.8 million for Ethereum.
| Displayed metric | Solana | Ethereum |
|---|---|---|
| 24-hour chain fees | About $1.10 million | $649,423 |
| 24-hour reported burns | $117,138 | $226,298 |
| 7-day chain fees | $5.93 million | $3.09 million |
| 7-day reported burns | $698,884 | $761,849 |
| 30-day chain fees | $23.58 million | $12.04 million |
| 30-day reported burns | $2.66 million | $2.80 million |
Exact window endpoints were not disclosed, and Ethereum's shared revenue table showed a different daily figure of $229,846. The comparison consequently applies to the displayed aggregates, with synchronization limits.
The longer windows also temper the daily headline. Ethereum's 30-day reported burn was only slightly larger than Solana's, even though its daily overview showed a much wider gap. Aggregate leadership over seven or 30 days does not mean either network led every individual day.
How fees reach validators, stakers and apps
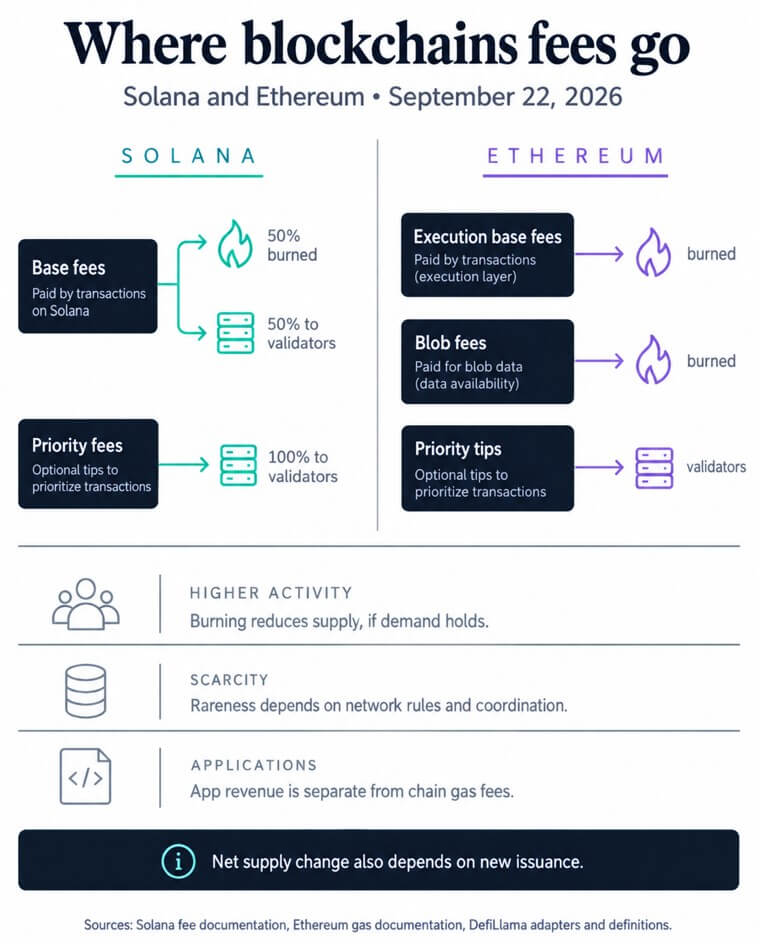
Under Solana's fee rules, the base charge is 5,000 lamports per signature. Half of that base fee is burned, and half goes to the validator producing the block. The validator receives all priority fees, which users pay for transaction priority.
That allocation makes fee composition important. A rise in priority fees increases validator receipts without directing that stream to burning, so higher total fees can coexist with a comparatively small burn figure.
Ethereum burns execution base fees, while priority tips go to validators. DefiLlama's Ethereum data-collection code also includes blob fees in both total fees and reported burns. Two similar totals for user spending could affect supply differently, depending on the kinds of fees paid.
The data-collection programs, known as adapters, estimate parts of these reported burns. DefiLlama's Solana adapter estimates base fees by multiplying transaction count by 5,000 lamports, although the protocol charges by signature.
Ethereum's adapter uses each block's minimum effective transaction gas price as a proxy for its execution base fee and obtains blob fees separately from Dune. Neither estimate should be presented as a fully reconciled measurement of tokens destroyed.
Burning reduces supply relative to what it would otherwise have been, and it does not credit a holder's wallet, establish that total supply is falling, or guarantee a price gain. Those are separate questions from how much users paid to transact.
A validator's receipts are not automatically everyone's receipts when staking through it. Solana's staking documentation describes inflationary rewards distributed to validators and delegated stake accounts, with commissions affecting what delegators receive.
The yield also depends on total stake and validator performance. These newly issued rewards are separate from user fees.
On July 2, 2025, Solana staking infrastructure project Jito announced a live upgrade that lets validators distribute priority fees to their stakers. Validators' choices and commissions determine the distribution, and a sharing mechanism does not turn all chain fees into a uniform return for SOL stakers.
For an ordinary holder, the relevant distinction is between owning the asset and participating in a particular reward arrangement.
A passive holder receives no validator payment merely because chain fees rise, while a staker needs to know which rewards are included and what deductions apply before treating a quoted yield as fee income.
Applications represent another destination for economic activity. The Sept. 22 overviews showed $7.7 million in 24-hour app revenue on Solana versus $1.9 million on Ethereum. App fees were $18.2 million and $8.5 million, respectively.
DefiLlama's definitions separate app metrics from gas fees. They also define chain REV as chain fees plus maximum extractable value (MEV) tips. REV can describe a broader stream of transaction-related spending, but adding it to chain fees would count those fees twice.
Valuation and issuance change the investment question
Ethereum's larger dollar burn sits against a much larger token valuation. The same Sept. 22 overview snapshots displayed market capitalizations of $335 billion for ETH and $69 billion for SOL. Nearly comparable 30-day reported burns represent a larger fraction of Solana's displayed market capitalization.
A holder's yield requires a separate calculation. It compares a period's estimated burning with a valuation at one moment, and it says nothing by itself about tokens created during that period. A larger gross burn relative to market value can coexist with issuance that more than offsets it.
Ethereum's supply mechanics make that distinction explicit: net supply depends on issuance and burning. Its Merge explainer's roughly 1,700 ETH-per-day example assumes about 14 million ETH staked, so it cannot serve as a current September 2026 issuance measurement.
Without matched-period issuance for both networks, these fee tables cannot establish either a net supply advantage or a superior investment return.
Solana's accepted SGP-0002 proposal calls for increasing annual disinflation from 15% to 30%, but explicitly depends on SIMD-0550 acceptance and activation. Its current monetary effect depends on implementation.
For holders comparing SOL and ETH, the decisive missing evidence is a matched-period account of tokens issued and burned, alongside the fees actually distributed after commissions.
The September snapshot shows stronger fee generation on Solana and a larger reported dollar burn on Ethereum. Turning either observation into a return claim requires knowing how much reaches the holder, how much supply is added, and what valuation the buyer pays.
The post Solana flips Ethereum in fees, while ETH holds the burn lead appeared first on CryptoSlate.